Need a Short Sale Real Estate Agent in Houston? Start With a Confidential Review
If you owe more on your home than it may sell for, are behind on payments, or are trying to avoid foreclosure, speaking with a short sale real estate agent early can help you understand your options. A short sale is not a typical home sale: your mortgage lender or servicer must agree to accept sale proceeds that are less than the outstanding loan balance.
At Vestera Realty, we help Greater Houston homeowners evaluate the property, prepare a market-informed selling strategy, market the home to qualified buyers, and coordinate the transaction with the parties involved. Every situation is different, so the first step is a private conversation—not a rushed decision.
What Does a Short Sale Real Estate Agent Do?
A short sale real estate agent represents the homeowner in the sale of a property where the anticipated net proceeds may not fully satisfy the mortgage payoff and other approved transaction costs. The seller still owns the property and still needs to market and sell it—but the lender or servicer must approve the final terms before closing.
Your agent’s role is to help bring order to a process with more moving parts than a conventional sale. That can include:
- Preparing a pricing analysis based on current local market data and the home’s condition.
- Creating a marketing plan designed to attract qualified buyers and support a credible offer.
- Coordinating the listing, offers, contract deadlines, title work, and lender-required documentation.
- Communicating with the lender or servicer and other transaction professionals as authorized by you.
- Helping you compare the practical questions: timing, potential cash contribution, lien releases, and the written terms of any approval.
The lender—not the real estate agent—decides whether to approve a short sale and on what terms. Fannie Mae’s servicing guidance, for example, requires the servicer to review the contract, valuation, settlement statement, and any subordinate-lien issues before closing. Read Fannie Mae’s current short-sale guidance
Could a Short Sale Be an Option for Your Houston Home?
A short sale may be worth exploring when selling at realistic market value is unlikely to produce enough money to pay the mortgage payoff and approved sale costs—and you are experiencing a hardship or need another path besides foreclosure. It is a loss-mitigation option, not an automatic approval.
Situations that often call for a confidential review include:
- You are behind on mortgage payments or have received foreclosure-related notices.
- A job change, medical issue, divorce, death in the household, or another hardship has changed your ability to keep the home.
- You need to relocate and the property value or payoff creates a gap.
- You own a property with multiple liens, HOA balances, or condition issues that complicate a normal sale.
Act promptly if you have a foreclosure timeline. The Consumer Financial Protection Bureau explains that a short sale is an alternative to foreclosure, but it still means selling and leaving the home. See CFPB’s homeowner overview
The Short Sale Process, Step by Step
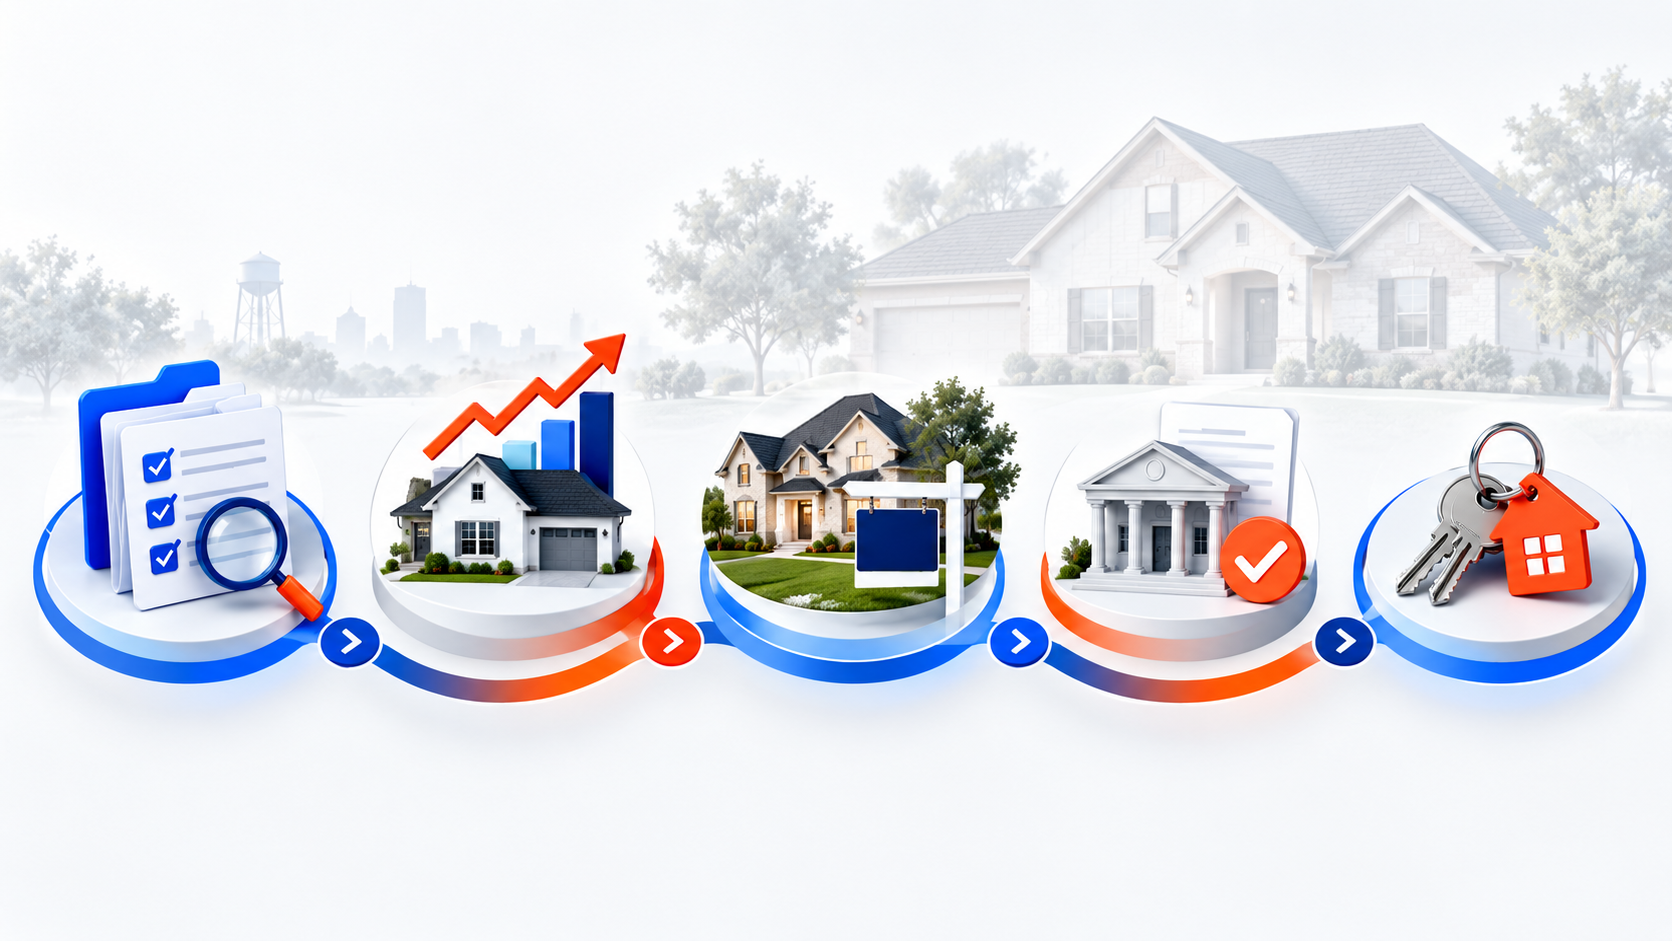
Confidential property and situation review
We discuss the property, estimated market value, mortgage payoff, lien information, timing, and your goals. We do not assume a short sale is the right answer before looking at the facts.
Prepare the sale strategy and lender package
Your servicer may request financial and hardship documentation. We help organize the real-estate side of the transaction and coordinate with your authorized contacts.
List and market the home
The property is positioned for the right buyer pool with professional marketing and a pricing strategy supported by local comparable sales.
Evaluate offers and submit the complete package
An accepted buyer offer is generally contingent on lender or servicer approval. The strongest offer is not always simply the highest price; terms, buyer readiness, timing, and required approvals matter.
Receive written approval and close
Review the approval letter carefully before closing. Confirm what it says about deficiency, any required contribution, lien releases, deadlines, and closing conditions with qualified legal and tax professionals.
Short Sale vs. Foreclosure: Why the Details Matter
Both options can affect your financial future, but they are not the same. A short sale is a voluntary sale that requires lender approval; foreclosure is the lender’s legal process to take ownership after default. Neither outcome should be described as “easy” or “credit-safe.”
One especially important issue is the unpaid balance. The CFPB advises homeowners to ask whether the lender will waive the deficiency—the remaining amount after the sale—before proceeding. [Its guidance explains why the written terms matter]. There can also be tax consequences when debt is forgiven, so this is the point to involve a tax professional and a Texas attorney.
For some loans, the servicer’s rules can also affect timing. Fannie Mae’s current guidance states that a servicer must acknowledge an initial offer within five business days and provide a written response within 30 calendar days after receiving a complete borrower response package, if required, and an initial offer. Individual files can take longer when information is incomplete, multiple liens exist, or another approval is required. [See the published timeframes].
Questions to Ask Before Hiring a Short Sale Real Estate Agent
Choose an agent based on process and communication—not a promise that no one can guarantee. Ask:
- How will you determine an accurate list-price strategy for my neighborhood and condition?
- Who will coordinate with my servicer, title company, and other authorized professionals?
- What documents should I begin gathering for the lender or servicer?
- How will you market the property to bring in qualified buyers?
- How often will I receive a meaningful update?
- What will I need to confirm in the lender’s written approval before I sign closing documents?
At Vestera Realty, our seller approach combines data-driven pricing, professional marketing, and straightforward communication. We serve homeowners across Greater Houston, including Sugar Land, Fort Bend County, Houston, Katy, Pearland, and surrounding communities.
Check out this article next